Market Brief · Colombia
Field Desk — reported on the ground

Colombia

A high-rate, cheap-currency market with the lowest investor-visa threshold of anywhere we cover — attached to a fiscal position that has been deteriorating for two years. Both halves of that sentence are the story.

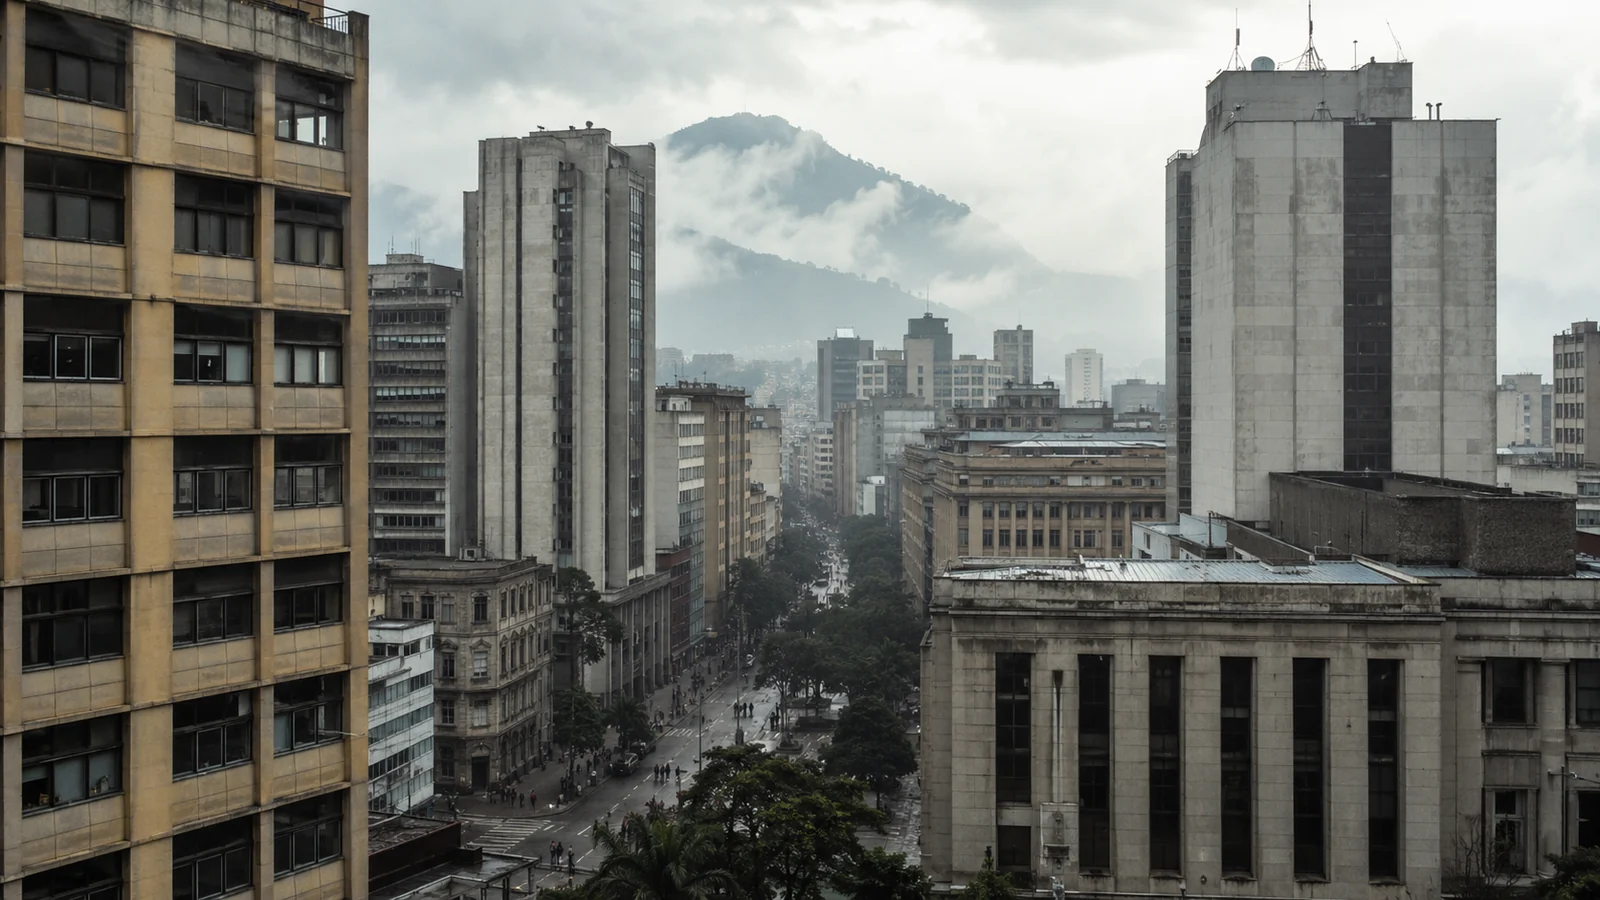
Colombian city centre under low cloud, mid-century concrete office towers with a forested mountain ridge behind

Illustration — AI-generated artwork, not documentary photography. Our desk is in Medellín, Antioquia.

On this page

  1. At a glance
  2. The case for, the case against
  3. The five routes in
  4. Rules of the road
  5. Exposure from outside Colombia
  6. What we’d verify first
  7. Field reports
  8. Free guides

At a glance

Colombia — key indicatorsVerified 10 Aug 2026
Policy rate12.00%Held by majority vote, 31 July 2026. Raised 75bp to 12% in July.
Headline inflation6.14%June 2026 print. Core steady around 6.0%. Target is 3%.
GDP growth (2026f)2.5%BanRep technical staff projection. 2025 outturn was 2.6%.
Unemployment8.0%National rate, end of June 2026 — still declining.
Public debt>61%Of GDP. Fiscal deficit around 6.2% after the fiscal rule was suspended.
Sovereign ratingSub-IGBelow investment grade at both Moody’s and S&P following downgrades.
Investor visa floor350×Monthly minimum wage, property route — roughly COP 612.8M in 2026.
Index statusEMConstituent of the MSCI Emerging Markets index, at a small weight.
Sources: Banco de la República board decision (31 Jul 2026) and minutes (5 Aug 2026); BBVA Research commentary on the July meeting; DANE via BanRep. Rates and prints move — check the current figure before acting on anything here.

The single most important thing to understand about Colombia right now is that its central bank is fighting in the opposite direction to most of the region. BanRep raised the policy rate to 12% in July 2026 and held it there at the end of the month, having reversed its cutting cycle earlier in the year when core inflation re-accelerated. Median analyst expectations in BanRep’s own July survey put December 2026 inflation at 6.6% and 2027 at 5.0% — both well above the 3% target.

Alongside the rate decision, the bank announced a programme to accumulate up to USD 4 billion in international reserves, with the first monthly auction called for 3 August 2026. That programme exists because the peso appreciated substantially through the year. If you are holding pesos, that appreciation is the thing that already happened, not the thing you are buying into.

The case for, the case against

What’s working

  • A 12% policy rate against ~6% inflation is a real yield most developed markets can’t match. That carry is the entire local-currency fixed income argument.
  • Domestic demand is genuinely strong. The economic activity index rose 4.1% year-on-year in May 2026, driven by services, and unemployment fell to 8.0% by end-June.
  • Remittances are a real stabiliser. They grew 8.1% to USD 8.7 billion in 2025, cushioning the external accounts in a way most peer markets don’t have.
  • The investor visa threshold is unusually low. Roughly USD 155,000–165,000 of qualifying property buys residency — a fraction of comparable programmes in Portugal, Panama, or the Caribbean.
  • Genuine legal openness to foreign capital. No restriction on foreigners owning property, no minimum capital for a SAS, and 100% foreign ownership permitted.

What isn’t

  • The fiscal position is deteriorating. Colombia suspended its fiscal rule in mid-2025. The deficit landed around 6.2% of GDP and public debt is above 61%.
  • Both Moody’s and S&P have downgraded and the sovereign sits below investment grade. That is a structurally higher cost of capital for everything in the country.
  • Inflation is going the wrong way. It re-accelerated in 2026 rather than converging, and the IMF does not see the 3% target reached until 2027 at the earliest.
  • Central bank independence has been publicly tested. The finance minister walked out of the March 2026 board meeting in protest at a rate hike — unusual for an institution independent since 1991.
  • The peso rally is behind you, not ahead of you. A currency that has already appreciated sharply, in a market the central bank is now buying dollars into, is a different trade than it was a year ago.
  • FDI is flat. It rose just 1.5% to USD 6.6 billion in 2025 — foreign capital is not exactly stampeding in.

Figures above from Banco de la República’s July 2026 board release and August minutes, BBVA Research’s note on the July meeting, and reporting on Colombia’s 2026 fiscal position. We have not modelled these, projected them, or adjusted them.

The five routes in

Every market brief on this site maps the same five routes. Here is how each one actually behaves in Colombia — with the friction called out, not the brochure version.

Route 01

Real estate

Foreigners face essentially no legal restriction on owning Colombian property. The friction is procedural: the promesa de compraventa, the notary, and getting title actually registered in your name. Envigado and Belén consistently offer better value per square metre than the El Poblado listings every expat guide points at.

Real estate pillar →
Route 02

Banking & moving money

Opening a Colombian account as a non-resident is possible but slow, and generally requires a cédula de extranjería. The bigger cost is usually the transfer itself — spread plus the 4x1000 financial transactions tax on local movements adds up faster than people budget for.

Banking pillar →
Route 03

Business formation

The SAS is the reason many people incorporate here at all: no minimum capital requirement, a single shareholder is fine, and 100% foreign ownership is permitted. Post-incorporation obligations — RUT, cámara de comercio renewal, accounting — are where people underestimate the ongoing cost.

Business pillar →
Route 04

Residency by investment

Two routes, both pegged to the monthly minimum wage: roughly 350× for the property route, 100× for a business investment. Because the 2026 minimum wage rose about 24%, both thresholds jumped overnight — a lot of published guides are still quoting 2025 numbers.

Residency pillar →
Route 05

Precious metals

Relevant here mainly as a hedge against the exact peso volatility that makes the carry trade attractive. Physical storage inside Colombia is not straightforward, which pushes most people toward holding metal outside the country.

Metals pillar →

Rules of the road

These are the structural rules that shape everything else. They change less often than rates do, but they change — and getting one of them wrong is considerably more expensive than mistiming an entry.

AreaWhat actually applies
Foreign property ownershipNo nationality-based restriction. Foreigners may hold freehold title in their own name, including in coastal and border areas — which distinguishes Colombia from Mexico and Indonesia.
Registering foreign investmentForeign capital brought in must be registered with Banco de la República through the exchange-market channel. This is the step that preserves your legal right to repatriate capital and profits later. Skipping it to save a fee is the single most consequential mistake we see.
Tax residencyTriggered by presence of more than 183 days within any rolling 365-day period. Colombian tax residents are taxed on worldwide income — this catches people who moved for the visa without modelling the tax consequence.
Financial transactions taxThe gravamen a los movimientos financieros, universally called 4x1000, applies to qualifying debits from Colombian accounts. Small per transaction, meaningful across a property purchase.
Company ownershipA SAS may be 100% foreign-owned with a single shareholder and no statutory minimum capital. A legal representative is required; residency is not.
CurrencyFreely floating. No capital controls in the Argentine sense, but all inbound and outbound investment flows move through the regulated exchange market and must be declared.

Structural rules as understood in August 2026. Colombian tax and exchange regulation is revised regularly, and a tax reform was under discussion during 2026. Confirm with a Colombian attorney or contador before you move money.

Exposure from outside Colombia

Not everyone reading this wants to move here, and you do not need to in order to take a position. The honest summary is that Colombia is a small allocation in most emerging-market products — it is an MSCI Emerging Markets constituent, but at a weight that means a broad EM fund gives you almost no Colombian exposure in practice.

For anyone wanting something more concentrated, single-country Colombia equity products exist — Global X’s MSCI Colombia ETF (ticker GXG) is the long-standing one — and several of the largest Colombian companies, including Bancolombia and Ecopetrol, trade as ADRs on US exchanges. Both routes carry the concentration and liquidity characteristics you would expect from a small single-country market, and both are exposed to the peso whether or not you think of yourself as taking a currency position.

The local-currency bond market is where the 12% policy rate actually shows up as yield, and it is also the hardest of these routes for a foreign individual to access directly without a local broker relationship.

We wrote up the currency side of this in detail: the case for — and against — buying Colombian pesos, and how the Colombian stock market actually works for foreigners.

Named products are mentioned because they are the recognised routes to this exposure, not as recommendations. We hold no position in them and earn nothing from mentioning them. Nothing on this page is investment advice.

What we’d verify first

Field reports — Colombia

Everything we’ve published on Colombia

Currency

The Case for Buying Colombian Pesos in 2026

The peso’s best run against the dollar in a decade — the real case for it, and the case against.
Real Estate

Buying Real Estate in Colombia as a Foreigner

The legal process from promesa de compraventa to registered title, and where foreigners get tripped up.
Real Estate

Medellín vs. Bogotá vs. Cartagena for Property Investment

Buyer profile, liquidity, and rental dynamics compared across the three biggest markets.
Residency

Colombia Residency by Investment: The 2026 Thresholds

Property route vs. business route — the two numbers that matter, and why they’re not the ones most sites quote.
Business

How to Form a SAS Company in Colombia

No minimum capital, one shareholder, foreign ownership allowed. What the paperwork actually looks like.
Banking

Opening a Colombian Bank Account as a Foreigner

Which banks will actually onboard you, what they ask for, and how long it really takes.
Banking

Moving Money to Colombia Without Losing a Chunk to Fees

Transfer methods compared, and the fee math nobody shows you up front.
Markets

The Colombian Stock Market for Foreigners

How the BVC works, what’s actually listed, and the access routes from outside the country.
Cost of Living

The Medellín Cost of Living Investment Case

What the low cost base actually does to the arithmetic, and where it’s eroding.
Metals

Gold and Silver as an Emerging-Market Currency Hedge

The other side of the peso trade, and what hedging actually costs you.
Mistakes

Common Mistakes Foreign Investors Make in Colombia

The recurring, expensive ones — most of them procedural rather than analytical.
Free — no email required

Three Colombia guides, straight download

Each one collapses a cluster of field reports into a single reference document. No signup, no gate, no drip sequence. Right-click and save.

Guide 01

Colombia Real Estate Investment Guide

The buying process end to end, city-by-city notes, and the 2026 visa-threshold math.

Download PDF
Guide 02

Moving Money to Colombia

Bank accounts, transfer methods, and the fee arithmetic nobody shows you up front.

Download PDF
Guide 03

SAS Formation Checklist

Every document, filing, and post-incorporation obligation, in the order you’ll hit them.

Download PDF
Field Desk noteColombia is the only market on this site we cover from inside. That’s worth something and it’s also worth being honest about its limits — living in Medellín makes us better on notaries, banks, and what a process actually feels like, and no better than anyone else on macro forecasting. Where this page states a number, it’s sourced. Where it states a judgement, it’s labelled as one.

← All market briefs